
A service business can be busy every day and still have no idea which jobs are actually making money.
You may know:
monthly revenue
and:
monthly profit
but still be unable to answer:
Was yesterday’s £1,200 plumbing job profitable?
Did that £8,000 electrical installation make enough margin?
Are maintenance jobs better than emergency repairs?
Which services should we market more aggressively?
That is why learning how to calculate gross profit per job is so useful.
Job-level profitability connects:
Quoted Price
↓
Actual Labor
↓
Actual Materials
↓
Other Direct Costs
↓
Gross Profit
↓
When you know these numbers, pricing decisions become much stronger.
Instead of saying:
“That felt like a good job.”
you can say:
“That job produced £480 gross profit at a 40% margin.”
That is a much better way to run a service business.
What Is Gross Profit Per Job?
Gross profit per job is the amount remaining after subtracting the direct costs required to complete that specific job.
A simple formula is:
Job Revenue − Direct Job Costs = Gross Profit
For example:
Job revenue:
£1,000
Direct costs:
£600
Gross profit:
£400
That £400 then contributes toward:
- office staff;
- rent;
- software;
- marketing;
- insurance;
- management;
- business profit.
Gross profit is not necessarily the final profit the owner keeps.
It is the amount available after direct job costs.
What Is Gross Margin Per Job?
Gross margin expresses gross profit as a percentage of job revenue.
Formula:
Gross Profit ÷ Job Revenue × 100
Using the same example:
Gross profit:
£400
Revenue:
£1,000
Gross margin:
40%
This lets you compare jobs of different sizes.
A £500 repair and a £10,000 installation can both be evaluated using margin.
Why Gross Profit Per Job Matters
Total monthly revenue can hide weak jobs.
Suppose you complete:
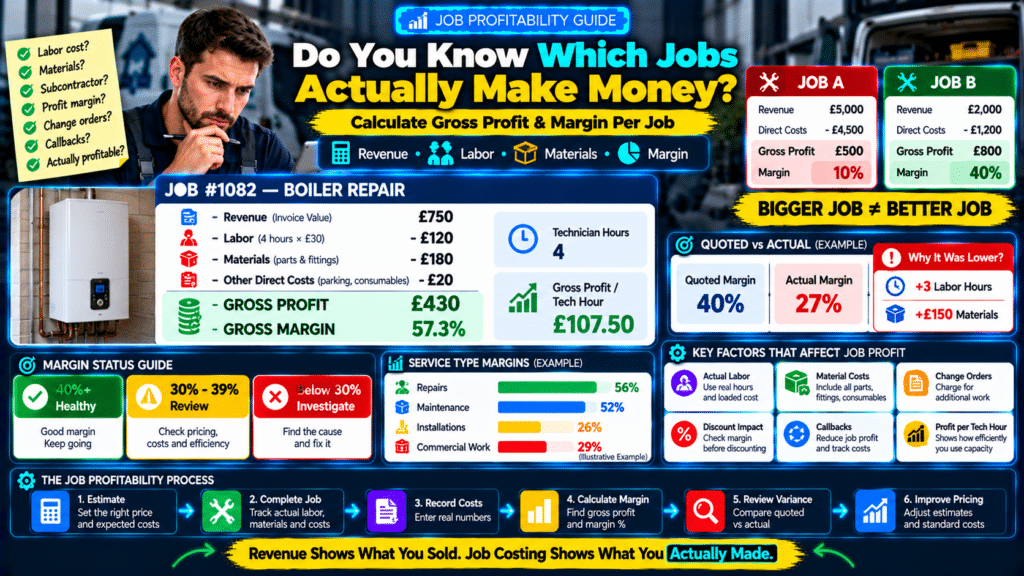
Job A
Revenue:
£5,000
Gross profit:
£500
Gross margin:
10%
Job B
Revenue:
£2,000
Gross profit:
£800
Gross margin:
40%
Job A generated more revenue.
Job B generated more gross profit.
That means the bigger job was not necessarily the better job.
Revenue Is Not Profit
This sounds obvious, but many service businesses still manage by revenue alone.
Example:
You complete a:
£10,000 installation.
Materials:
£5,000
Labor:
£2,000
Subcontractor:
£1,000
Other direct costs:
£500
Total direct costs:
£8,500
Gross profit:
£1,500
Gross margin:
15%.
A £10,000 invoice may look impressive.
But the job produced relatively weak margin.
Step 1: Record Job Revenue
Start with the actual selling price.
Include:
- approved additional work;
- change orders;
- upgrades.
Do not only use the original quote if the final invoice changed.
Example
Original quote:
£2,500
Additional approved work:
£300
Final job revenue:
£2,800
Use:
£2,800
for the final job profitability calculation.
Step 2: Record Actual Labor Cost
Do not use only:
hours quoted.
Use:
hours actually worked.
Suppose:
Estimated labor:
6 hours.
Actual labor:
9 hours.
If true loaded technician cost is:
£30/hour
actual labor cost:
9 × £30 = £270
Using the quoted six hours would hide the real cost.
What Is Loaded Labor Cost?
Loaded labor cost is more than hourly wage.
It may include:
- wage;
- payroll costs;
- benefits;
- employer contributions;
- paid leave;
- other employment costs.
For example:
Technician wage:
£20/hour
True loaded cost:
£28/hour
For job costing, using the more realistic number gives you a better view of profitability.
Step 3: Record Materials
Use actual material cost.
Include:
- parts;
- fittings;
- cable;
- pipe;
- consumables;
- replacement units.
For example:
Boiler component:
£120
Fittings:
£25
Consumables:
£10
Total materials:
£155
Do not ignore small items just because they are inexpensive individually.
Across hundreds of jobs, they matter.
Step 4: Include Subcontractors
If another contractor contributes to the job, their cost is usually a direct job cost.
Examples:
- electrician;
- plasterer;
- roofer;
- scaffold company;
- skip hire;
- specialist engineer.
If subcontractor invoice is:
£750
that should be included in job costing.
Step 5: Include Job-Specific Expenses
Other direct costs may include:
- parking;
- permits;
- disposal;
- equipment hire;
- delivery;
- tolls;
- job-specific travel.
You do not need to overcomplicate small expenses.
But significant costs should be included.
Example Direct Cost Breakdown
Job revenue:
£3,000
Labor:
£600
Materials:
£1,000
Subcontractor:
£300
Equipment hire:
£100
Total direct cost:
£2,000
Gross profit:
£1,000
Gross margin:
33.3%.
Step 6: Calculate Gross Profit
Formula:
Revenue − Direct Costs = Gross Profit
Example:
Revenue:
£3,000
Direct costs:
£2,000
Gross profit:
£1,000
Simple.
But useful only if the direct costs are accurate.
Step 7: Calculate Gross Margin
Formula:
Gross Profit ÷ Revenue × 100
£1,000 ÷ £3,000:
33.3%
Now you can compare it against:
- company target;
- other jobs;
- other service types.
Example: Plumbing Repair
Revenue:
£480
Labor:
2 hours × £30:
£60
Materials:
£90
Parking:
£10
Total direct cost:
£160
Gross profit:
£320
Gross margin:
66.7%
This may be a very attractive service.
Example: Boiler Installation
Revenue:
£3,500
Labor:
£600
Boiler and materials:
£1,900
Disposal:
£100
Total direct cost:
£2,600
Gross profit:
£900
Gross margin:
25.7%
The installation generates more gross profit pounds than the repair.
But a much lower margin percentage.
Both metrics matter.
Gross Profit Pounds vs Gross Margin Percentage
Do not focus on only one.
Gross Profit Pounds
Tells you:
how much money the job contributed.
Gross Margin Percentage
Tells you:
how efficiently the job converted revenue into gross profit.
Example:
Job A
Revenue:
£10,000
Gross profit:
£2,000
Margin:
20%
Job B
Revenue:
£3,000
Gross profit:
£1,500
Margin:
50%
Job A produces more gross profit pounds.
Job B has stronger margin.
Which is better depends on:
- time;
- risk;
- capacity;
- cash flow.
Include Technician Time Correctly
A common mistake is:
We already pay the technician salary, so labor cost doesn’t matter.
It absolutely matters for job profitability.
Technician time is a scarce resource.
If a job takes:
10 hours
instead of:
5
that affects how much other work the technician could complete.
Track actual time.
Track Estimated vs Actual Labor
Example:
Estimated:
5 hours
Actual:
8 hours
Variance:
+3 hours
If loaded labor cost is:
£30/hour
extra cost:
£90
This may explain why the job missed margin target.
Track Estimated vs Actual Materials
Estimated:
£500
Actual:
£650
Variance:
+£150
Possible reasons:
- price increase;
- waste;
- incorrect estimate;
- extra materials not charged to customer.
This should inform future quoting.
Track Quoted Margin vs Actual Margin
Example:
Quoted margin:
40%
Actual margin:
27%
That is a significant difference.
Ask:
Why?
Possible reasons:
- labor ran over;
- materials increased;
- scope changed;
- discount applied;
- additional work not charged.
This is one of the most valuable job-costing reviews you can perform.
Change Orders Protect Gross Profit
A customer asks for extra work.
Technician says:
No problem.
Work takes:
2 extra hours
and uses:
£100 materials.
If the business does not charge for it:
gross profit drops.
Use change orders.
Example
Original job:
£2,000
Additional work:
£350
Additional direct cost:
£160
Additional gross profit:
£190
If the extra work is approved and billed, margin can be protected.
If not:
the company absorbs the cost.
Discounts Affect Gross Profit Directly
Suppose:
Normal price:
£1,000
Direct costs:
£600
Gross profit:
£400
Margin:
40%
Give customer:
10% discount
New price:
£900
Direct costs remain:
£600
Gross profit:
£300
Margin:
33.3%
A 10% discount reduced gross profit from:
£400 to £300
which is a:
25% reduction in gross profit.
Discounts can have a much bigger profitability impact than owners realize.
Calculate the Margin Impact Before Discounting
If technicians or sales staff can offer discounts:
give clear limits.
For example:
Up to 5% without approval
above that:
manager approval.
The exact policy depends on the business.
The goal is to protect margin.
Job Costing and Fixed Overhead
Gross profit does not usually include general overhead such as:
- office rent;
- admin salaries;
- software;
- general insurance.
Those are covered by gross profit across all jobs.
That is why the company needs enough total gross profit to cover overhead and create net profit.
This connects directly with break-even revenue.
Example
Monthly fixed overhead:
£25,000
Average gross profit per job:
£250
You need approximately:
100 jobs
just to generate:
£25,000 gross profit
before creating operating profit.
That is why gross profit per job is so important.
Gross Profit Per Technician Hour
A useful metric is:
Gross Profit ÷ Technician Hours
Example:
Gross profit:
£600
Technician hours:
4
Gross profit per technician hour:
£150
Compare another job:
Gross profit:
£800
Technician hours:
10
Gross profit per technician hour:
£80
The second job makes more total gross profit but uses much more field capacity.
This metric helps with:
- service mix;
- scheduling;
- marketing.
Example
Emergency Repair
Gross profit:
£500
Technician time:
2.5 hours
Gross profit per tech hour:
£200
Installation
Gross profit:
£2,000
Technician time:
30 hours
Gross profit per tech hour:
£66.67
Installation produces more total gross profit.
Repair produces much more profit per technician hour.
That can influence what you want to grow.
Track Gross Profit by Service Type
For example:
| Service | Revenue | Gross Profit | Margin |
|---|---|---|---|
| Emergency Repairs | £25K | £14K | 56% |
| Maintenance | £18K | £10K | 55.6% |
| Installations | £60K | £15K | 25% |
| Commercial Work | £40K | £11K | 27.5% |
Now you can see:
installations produce large revenue.
Repairs produce much stronger margins.
Marketing decisions can reflect that.
Track Gross Profit by Customer Type
Example:
Residential
Average margin:
45%
Commercial
Average margin:
28%
Commercial may still be attractive because:
- job size larger;
- repeat work;
- lower acquisition cost.
But the difference should be understood.
Track Gross Profit by Lead Source
This is where marketing and finance connect.
Google Ads Jobs
Revenue:
£40K
Gross profit:
£16K
Ad spend:
£7K
Contribution after ads:
£9K
Referral Jobs
Revenue:
£25K
Gross profit:
£12K
Referral cost:
£1K
Contribution after referral cost:
£11K
Referral business may generate less revenue but more useful profit.
Job Profitability Should Influence Marketing
Do not market every service equally.
Suppose:
Service A
Average job:
£2,000
Gross margin:
20%
Service B
Average job:
£800
Gross margin:
55%
If Service B also has strong demand:
it may deserve more marketing attention.
Gross Margin Targets Should Vary by Service
One universal margin target may not fit all job types.
For example:
Small Repair
Higher margin.
Large Installation
Lower percentage margin but larger profit pounds.
The important thing is knowing the acceptable range for each service.
Create Job Margin Bands
Example:
Green
40%+
Healthy.
Yellow
30–39%
Review.
Red
Below 30%
Investigate.
These are illustrative only.
Your actual thresholds depend on:
- trade;
- overhead;
- pricing model.
Review Low-Margin Jobs
Do not just look at averages.
Review individual jobs that performed poorly.
Ask:
- Was labor underestimated?
- Were materials higher?
- Was there rework?
- Was price discounted?
- Was scope unclear?
- Did we fail to charge for extras?
The goal is:
identify repeatable causes.
Example Job Review
Job #1056
Quoted:
£2,500
Target margin:
40%
Actual revenue:
£2,500
Actual direct cost:
£2,000
Actual gross profit:
£500
Margin:
20%
Reason:
- 6 extra labor hours;
- £250 unplanned materials.
Action:
- increase labor allowance;
- update estimating checklist.
That job just taught you how to price the next one better.
High-Margin Does Not Always Mean Best
Be careful.
A job with:
70% gross margin
may only create:
£70 gross profit.
Another job at:
30% margin
may create:
£3,000 gross profit.
You need to consider:
- gross profit pounds;
- technician time;
- risk;
- customer lifetime value.
Use multiple metrics.
Cash Flow Matters Too
A highly profitable commercial project may not pay for:
60 days.
A lower-margin residential repair may pay:
same day.
Both affect the business differently.
This is why job profitability should be considered alongside cash flow.
Job Profitability vs Customer Lifetime Value
A first job may have modest margin.
But the customer may later buy:
- maintenance;
- repairs;
- upgrades.
Do not judge every customer relationship from one invoice.
Still, individual job economics should remain visible.
Track Callbacks Against the Original Job
Suppose a job initially generated:
£400 gross profit.
Then requires a callback costing:
£120.
Adjusted gross contribution becomes:
£280.
Quality problems reduce profitability.
This is why callbacks should be linked to original jobs.
Track Warranty Costs Too
If a job repeatedly generates:
- free return visits;
- replacement materials;
the actual profitability may be much worse than the original job report suggests.
For larger businesses, warranty reserves or warranty cost tracking can improve accuracy.
Build a Job Profitability Dashboard
For each job, track:
Job Revenue
Labor Hours
Labor Cost
Materials
Other Direct Costs
Gross Profit
Gross Margin
Gross Profit per Technician Hour
Callback Cost
This creates powerful management data.
Example Job Dashboard
Job #1082
Service:
Boiler Repair
Revenue:
£750
Labor Cost:
£120
Materials:
£180
Other Direct Costs:
£20
Gross Profit:
£430
Gross Margin:
57.3%
Technician Hours:
4
Gross Profit / Tech Hour:
£107.50
Now you understand the job.
Build a Monthly Service Profitability Report
Example:
Repairs
Revenue:
£30K
Gross Profit:
£17K
Margin:
56.7%
Installations
Revenue:
£70K
Gross Profit:
£20K
Margin:
28.6%
Maintenance
Revenue:
£20K
Gross Profit:
£12K
Margin:
60%
This tells management:
- what is growing;
- what is profitable;
- what needs pricing review.
Track Margin Trends
Do not only track current month.
Example:
January
42%
February
40%
March
37%
April
34%
Gross margin is declining.
Possible causes:
- material costs rising;
- discounting;
- labor inefficiency.
Investigate before the decline becomes serious.
Use Historical Job Data to Improve Estimates
Your job-costing system should feed your estimating system.
If the last 20 jobs of a certain type average:
7.5 technician hours
stop quoting:
5 hours.
Actual data should improve future pricing.
Example
Quoted labor allowance:
4 hours
Historical average:
6.2 hours
Update standard estimate.
That can immediately improve margins.
Create a Price Book From Real Job Data
For common services, track:
- actual labor;
- actual material;
- target margin.
Then build standardized pricing.
This creates:
Job Data
↓
Better Price Book
↓
Better Estimates
↓
Better Margins
↓
More Reliable Profit
Do Not Wait Until Year-End
If you only discover poor profitability when your accountant prepares annual accounts:
it is too late to fix those jobs.
Review job profitability:
- weekly;
- monthly.
Especially for:
- installations;
- large projects;
- new service types.
Job Costing for Small Jobs
You do not need a 20-line cost report for every:
£80 service call.
For smaller jobs, use standardized costs where appropriate.
Example:
Standard labor cost:
£45
Average materials:
£10
This can make tracking practical without creating excessive admin.
Job Costing for Large Jobs
For larger projects, track more detail:
- labor by technician;
- subcontractors;
- materials;
- equipment;
- permits;
- change orders;
- warranty costs.
The larger the financial risk:
the more detail is justified.
Common Job Costing Mistakes
Using Quoted Labor Instead of Actual Labor
You need the true cost.
Forgetting Small Materials
Small costs add up.
Ignoring Subcontractors
Direct cost must include them.
Not Tracking Additional Work
Protect margin through approvals.
Giving Discounts Without Checking Margin
Discounts reduce profit quickly.
Ignoring Callbacks
Actual job profitability becomes overstated.
Tracking Revenue Only
Revenue is not profit.
Looking Only at Margin Percentage
Profit pounds matter too.
Not Comparing Estimated vs Actual
You miss the learning opportunity.
No Service-Level Reporting
You cannot see which services are strongest.
Job Profitability Checklist
For each major job, track:
- Final revenue
- Actual technician hours
- Loaded labor cost
- Materials
- Subcontractor cost
- Equipment / permits
- Change orders
- Discounts
- Callback cost
- Gross profit
- Gross margin
- Gross profit per technician hour
- Estimated vs actual margin
- Reason for major variance
Gross Profit per Technician Hour
Gross profit per job tells you which jobs make money. Gross profit per technician hour tells you how well you use your team’s time. To work it out, divide the gross profit from your jobs by the technician hours spent on them, including travel if you want the full picture.
Why This Metric Matters
A service business has limited technician capacity.
You may have:
- 3 technicians;
- 5 technicians;
- 20 technicians.
But each technician only has a limited number of working hours.
If too many of those hours are spent on jobs that produce weak margins, the business may remain busy without becoming more profitable.
Gross profit per technician hour helps you see:
how productive your field capacity is financially.
Multiple Technicians on One Job
Suppose two technicians work:
5 hours each.
Total technician hours:
10
Do not divide profit by:
5 hours.
Use:
10 technician hours.
Example:
Gross profit:
£1,200
Technician hours:
10
Gross profit per tech hour:
£120
This is critical for installations where several employees work together.
What Counts as Technician Hours?
You need a consistent definition.
Possible choices include:
On-Site Productive Hours
Time actively completing customer work.
Job Hours
Includes:
- travel;
- preparation;
- on-site work;
- documentation.
Paid Hours
All paid technician hours.
For job profitability, many businesses start with:
actual hours charged to the job.
For capacity planning, you may also use:
available hours.
Do not mix definitions from one month to another.
Productive Hours vs Available Hours
Suppose a technician works:
160 paid hours/month
but spends:
120 hours
on productive job work.
Gross profit generated:
£12,000
Gross Profit per Productive Hour
£12,000 ÷ 120:
£100
Gross Profit per Available Hour
£12,000 ÷ 160:
£75
Both are useful.
The first shows:
job productivity.
The second shows:
overall capacity efficiency.
Travel Time Affects Overall Profit per Hour
Imagine Technician A has:
£100 gross profit per productive hour
but spends:
35% of their day traveling.
Technician B produces:
£90 gross profit per productive hour
but travels only:
15%.
Overall available-hour profitability may favor Technician B.
Routing matters.
Technician Comparison Example
Alex
Gross profit:
£11,000
Productive hours:
110
GP/productive hour:
£100
Callback rate:
2%
James
Gross profit:
£12,000
Productive hours:
150
GP/productive hour:
£80
Callback rate:
1%
Alex creates more profit per hour.
James creates more total gross profit with slightly better quality.
Both can be strong performers.
Do Not Improve the Metric by Cutting Quality
A bad strategy:
- skip testing;
- rush jobs;
- reduce necessary materials.
This may improve short-term numbers and create:
- callbacks;
- complaints;
- warranty cost.
Quality must remain part of the scorecard.
Example Before and After
Before
Gross profit:
£48,000
Available technician hours:
800
GP/available hour:
£60
Improvements
- reduce callbacks;
- improve routing;
- raise pricing selectively;
- reduce material waste.
After
Gross profit:
£58,000
Same available hours:
800
GP/available hour:
£72.50
Increase:
£12.50/hour
Total additional gross profit:
£10,000/month
No additional technician required.
Use the Metric Before Hiring
Before adding another technician:
ask:
Are we using existing technician hours profitably?
If GP/available hour is low because utilization is weak:
hiring more capacity may make things worse.
If:
- utilization is strong;
- GP/hour is healthy;
- demand exceeds capacity;
then a new hire may make sense.
Sources and Further Reading
These official resources back up the methods in this guide and are worth reading alongside it.
- What kind of records should I keep (IRS): the income and expense records your job costing should be built on.
- Manage your finances (U.S. Small Business Administration): bookkeeping, financial statements and cash versus accrual accounting.
- Break-even point (U.S. Small Business Administration): the fixed costs ÷ contribution margin formula and a free break-even calculator.
Related guides
- How to Improve Gross Margin in a Service Business Without Just Raising Prices
- Revenue vs Profit vs Cash Flow: What Service Business Owners Need to Know
- How to Calculate Break-Even Revenue for a Service Business
- Tools, Software and Automation for Trades: Start Here
Frequently Asked Questions
How do I calculate gross profit per job?
Use:
Job Revenue − Direct Job Costs = Gross Profit
Direct costs may include:
- labor;
- materials;
- subcontractors;
- job-specific expenses.
How do I calculate gross margin per job?
Use:
Gross Profit ÷ Job Revenue × 100
Should technician labor be included?
Yes.
If technician labor is a direct cost of delivering the service, it should normally be included in job costing.
Should overhead be included in gross profit per job?
General business overhead is usually not included in gross profit.
Gross profit contributes toward covering overhead.
What is a good gross margin?
There is no universal target.
It varies by:
- service;
- trade;
- cost structure.
Use your own business economics and financial goals.
Should I track every job?
Ideally, major and repeatable jobs should be tracked.
For very small jobs, standardized costing may be more practical.
Why is gross profit per technician hour useful?
It shows how much gross profit a job generates relative to the field capacity it consumes.
Can a high-revenue job be unprofitable?
Yes.
If labor, materials, and other direct costs are too high, a large job may produce weak or negative profit.
Should callbacks be included?
For accurate operational profitability, callback costs should be linked back to the original job where practical.
How often should job profitability be reviewed?
Weekly or monthly review works well for many service businesses, with immediate review for unusually large or low-margin jobs.
Conclusion
Learning how to calculate gross profit per job gives service-business owners a much clearer picture of what is actually driving profitability.
Do not stop at:
Job Revenue: £5,000
Track:
Revenue
↓
Labor
↓
Materials
↓
Other Direct Costs
↓
Gross Profit
↓
Gross Margin
Then go one step further:
Gross Profit ÷ Technician Hours
This tells you not only:
which jobs make money
but also:
which jobs use your field capacity most effectively.
Use job-level data to improve:
- pricing;
- estimating;
- technician scheduling;
- service mix;
- marketing.
If a job misses margin target:
investigate.
Was it:
labor?
materials?
scope?
discounting?
callbacks?
Then use the answer to improve the next quote.
The real goal of job costing is not to create more spreadsheets.
It is to make sure the business learns from every job.
A healthy financial system should connect:
Estimate
↓
Job
↓
Actual Cost
↓
Gross Profit
↓
Better Future Pricing
That is how job-level data becomes better company-level profit.



1 thought on “How to Calculate Gross Profit Per Job in a Service Business”
Pingback: Customer Lifetime Value for a Service Business (LTV Guide)