
One of the easiest ways for a service business to stay busy and still struggle financially is to price jobs incorrectly.
A plumber can complete ten jobs.
An electrician can have a full calendar.
A landscaper can work six days a week.
A cleaning company can keep adding customers.
But if each job is priced too low, more work can actually create more pressure.
That is why learning how to price service jobs properly matters.
A good price should cover more than:
materials + technician wages.
It also needs to contribute toward:
- fuel;
- vehicles;
- insurance;
- software;
- office staff;
- marketing;
- tools;
- rent;
- accounting;
- callbacks;
- taxes where applicable;
- business profit.
A useful pricing framework looks like:
Direct Labor
Materials
Other Direct Costs
Overhead Allocation
Profit
=
Selling Price
The exact numbers will differ between businesses.
But the principle is the same:
every job should contribute toward keeping the entire business healthy.
Why Guessing at Prices Is Dangerous
A common pricing method is:
“This feels like a £300 job.”
That may occasionally work.
But it creates several problems.
The owner may forget:
- travel time;
- disposal;
- small materials;
- office administration;
- payment fees;
- vehicle cost;
- warranty risk.
Two similar customers may also receive completely different prices because the estimate depends on whoever is quoting that day.
A better system gives you a repeatable way to calculate prices.
Start With Your Real Cost
Before deciding how much to charge, understand what the job actually costs the business.
There are two major types of cost:
Direct Costs
Costs directly associated with that specific job.
Examples:
- technician labor;
- materials;
- subcontractors;
- equipment rental;
- disposal fees;
- permits.
Overhead
Costs required to run the business but not tied neatly to one individual job.
Examples:
- insurance;
- office salaries;
- software;
- rent;
- advertising;
- vehicles;
- accounting.
Both must ultimately be paid for by your customers.
Step 1: Calculate Labor Cost Properly
Many businesses underestimate labor because they look only at hourly wages.
Suppose a technician earns:
£20 per hour.
It is tempting to think:
2-hour job = £40 labor cost.
But the real employment cost may be higher.
Depending on your business and location, labor cost can also include:
- payroll taxes;
- pension or benefits;
- paid leave;
- training;
- uniforms;
- insurance;
- non-billable time.
So the technician’s true hourly cost might be closer to:
£27 per hour
rather than:
£20.
Billable Hours Matter
A technician may be paid for:
40 hours per week
but not produce:
40 billable hours.
Time may be spent on:
- driving;
- collecting materials;
- team meetings;
- training;
- cancellations;
- vehicle loading;
- paperwork.
Suppose a technician is paid for:
40 hours
but only completes:
28 billable hours.
Your pricing needs to recover the cost of the entire working week from those 28 billable hours.
This is one reason simply multiplying the wage by job duration can lead to underpricing.
Example Labor Calculation
Suppose the true weekly employment cost is:
£900
and the technician produces:
30 billable hours.
Then labor cost per billable hour is:
£900 ÷ 30 = £30
That means a two-hour job already uses:
£60
of labor before:
- materials;
- overhead;
- profit.
Step 2: Calculate Material Cost
Material pricing sounds straightforward.
But businesses often lose margin through small items.
Imagine a plumbing repair uses:
- valve: £22;
- fittings: £8;
- pipe: £6;
- sealant: £3.
Total:
£39
But you may also have:
- purchasing time;
- delivery fees;
- wasted materials;
- stock holding;
- damaged items.
That is why many businesses apply a markup to materials rather than passing them through at exact purchase cost.
Material Cost vs Material Selling Price
If something costs you:
£100
and you charge the customer:
£100
you have recovered the item cost.
But you have earned nothing for:
- ordering it;
- storing it;
- collecting it;
- replacing damaged stock;
- financing inventory.
This is why trade businesses often add a markup.
Step 3: Include Other Direct Costs
Some jobs have additional costs.
For example:
Roofing
- scaffolding;
- skip hire;
- waste disposal.
Landscaping
- machinery hire;
- soil delivery;
- plant transport.
Electrical
- permits;
- specialist testing equipment.
Cleaning
- specialist chemicals;
- parking;
- access charges.
If the job creates the cost, include it in the estimate.
Step 4: Calculate Your Business Overhead
This is where many pricing systems fail.
A technician may only see:
labor + materials.
But the business must pay for much more.
Common overhead includes:
- business insurance;
- public liability insurance;
- vehicle insurance;
- fuel;
- software;
- office staff;
- phones;
- internet;
- advertising;
- website;
- accountant;
- equipment replacement;
- rent;
- utilities;
- training.
Example Monthly Overhead
Imagine a service company has:
| Expense | Monthly Cost |
|---|---|
| Office / Storage | £1,200 |
| Vehicles & Insurance | £1,800 |
| Fuel | £1,000 |
| Software | £400 |
| Marketing | £2,000 |
| Office Staff | £3,000 |
| Accounting / Admin | £600 |
| Insurance | £500 |
| Miscellaneous | £500 |
Total monthly overhead:
£11,000
Those costs do not disappear because they are not listed on a customer invoice.
Your jobs must collectively generate enough gross profit to cover them.
Allocating Overhead to Jobs
There are several ways to allocate overhead.
One simple method is:
Overhead per billable hour.
Suppose the company has:
440 billable technician hours per month
and monthly overhead is:
£11,000.
Overhead per billable hour:
£11,000 ÷ 440 = £25
So every billable technician hour needs to contribute approximately:
£25
toward overhead.
Example Two-Hour Job
Labor cost:
£60
Overhead allocation:
£50
Materials:
£40
Direct job cost before profit:
£150
If you charge:
£160
you may technically make money on paper.
But the profit is tiny.
This is why proper pricing must include a profit target.
Step 5: Understand Markup vs Profit Margin
These terms are often confused.
They are not the same.
Markup
Markup measures profit relative to your cost.
If something costs:
£100
and you add:
50% markup
the selling price becomes:
£150.
Profit:
£50.
Profit Margin
Margin measures profit as a percentage of the selling price.
Using the same example:
Selling price:
£150
Cost:
£100
Profit:
£50
Profit margin:
£50 ÷ £150 = 33.3%
So:
50% markup ≠ 50% margin.
This distinction is extremely important.
Margin Formula
Use:
Profit Margin = Profit ÷ Selling Price × 100
Selling Price From Desired Margin
If your total job cost is:
£500
and you want:
30% gross margin
you cannot simply add:
30%.
That would give:
£650
and a margin of only about:
23%.
Instead use:
Selling Price = Cost ÷ (1 − Desired Margin)
For a 30% margin:
£500 ÷ 0.70 = £714.29
That produces approximately a 30% gross margin.
Example Pricing Calculation
Let’s price a boiler repair.
Labor
2.5 hours at true labor cost of £30/hour:
£75
Materials
Parts cost:
£110
Other Direct Costs
Parking and disposal:
£15
Overhead Allocation
2.5 hours × £25:
£62.50
Total Cost
£75 + £110 + £15 + £62.50:
£262.50
Now assume the company targets a:
35% gross margin.
Selling price:
£262.50 ÷ 0.65
Approximately:
£403.85
You might round the final quote according to your pricing system.
For example:
£405
or:
£410.
That is very different from simply saying:
“The parts cost £110, so £250 sounds fair.”
Gross Profit vs Net Profit
Do not confuse these.
Gross Profit
Selling price minus direct job costs and your chosen job-costing structure.
Net Profit
What remains after the wider business expenses and other costs are accounted for.
A company can have good gross margins and still produce weak net profit if:
- overhead is too high;
- marketing is inefficient;
- vehicles are expensive;
- office costs are uncontrolled.
Pricing is only one part of profitability.
But it is a very important part.
What Is a Good Profit Margin?
There is no universal margin that every service business should use.
Different industries have different:
- labor intensity;
- material costs;
- competition;
- risk;
- overhead.
Instead of copying another company’s percentage, determine what your own business needs.
Your target should account for:
- operating costs;
- desired owner compensation;
- reinvestment;
- risk;
- growth.
Do Not Copy Competitor Prices Blindly
A competitor charging:
£100
does not mean you should charge:
£100.
Their business may have:
- lower overhead;
- cheaper labor;
- different quality;
- different service scope.
Or they may simply be pricing badly.
Use competitor pricing as market information.
Do not use it as your complete pricing system.
Hourly Pricing vs Fixed Pricing
One major decision is whether to charge:
hourly
or:
fixed price.
Both have advantages.
Hourly Pricing
The customer pays based on:
- hours worked;
- materials.
Example:
£90/hour + materials
Advantages
- protects against uncertain job duration;
- simple to calculate;
- useful for diagnosis.
Disadvantages
Customers may worry about:
- final cost;
- technician speed;
- open-ended bills.
Fixed Pricing
Customer receives the price before work begins.
Example:
Boiler repair: £395
Advantages
- clear customer expectation;
- easier approval;
- rewards efficient technicians;
- easier sales conversation.
Disadvantages
If the estimate is wrong, the business absorbs the difference.
Fixed pricing requires good historical job-cost data.
When Hourly Pricing Works Well
Hourly pricing can make sense for:
- diagnosis;
- troubleshooting;
- unknown conditions;
- specialist consultancy;
- open-ended repairs.
When Fixed Pricing Works Well
Fixed pricing works particularly well for repeatable services such as:
- boiler servicing;
- outlet replacement;
- drain cleaning;
- standard cleaning packages;
- routine maintenance.
The more predictable the work is, the easier it becomes to price consistently.
Build a Price Book
A price book is a standardized list of:
- services;
- materials;
- labor allowances;
- selling prices.
Instead of every technician inventing a number, they select an established service.
For example:
Replace Standard Tap
Labor allowance:
1.5 hours.
Materials allowance:
£75.
Selling price:
£295.
Consumer Unit Replacement
Labor allowance:
6 hours.
Materials allowance:
£450.
Selling price:
£1,350.
The actual numbers should come from your business data.
Why Price Books Help
A price book can improve:
- consistency;
- speed;
- margins;
- technician confidence;
- customer experience.
Without one:
Technician A may quote:
£450
while Technician B quotes:
£620
for nearly identical jobs.
That creates unnecessary inconsistency.
Include Travel Time
Travel is not free.
A technician driving:
45 minutes each way
has used:
1.5 working hours.
Even if that time is not shown as a separate invoice line, the pricing model must recover it somehow.
Options include:
- minimum call-out charge;
- travel zones;
- higher fixed prices;
- service-area restrictions.
Create a Minimum Service Charge
Small jobs can be surprisingly expensive.
Imagine a job takes:
20 minutes.
But the technician also spends:
- 25 minutes driving there;
- 20 minutes driving back;
- 10 minutes parking and preparing;
- 10 minutes processing payment.
That “20-minute job” may consume:
85 minutes.
This is why many service businesses use a:
minimum service charge.
It helps cover the cost of putting a technician on the road.
Emergency and After-Hours Pricing
Emergency work may justify different pricing because it can:
- disrupt normal scheduling;
- require overtime;
- involve night or weekend work;
- require immediate dispatch.
A clear system might include:
Standard Hours
Normal rate.
Evening
Higher call-out rate.
Weekend
Higher rate.
Emergency / Holiday
Premium rate.
The customer should understand the pricing before work begins whenever practical.
Charge for Expertise, Not Just Time
A skilled electrician may solve a problem in:
30 minutes
that an inexperienced person would spend:
3 hours
diagnosing.
Pricing purely by time can punish expertise.
The customer is paying for:
- training;
- certification;
- tools;
- experience;
- correct diagnosis.
This is another reason fixed pricing can work well for experienced service businesses.
Add Contingency to Uncertain Jobs
Some projects have more risk than others.
Examples:
- excavation;
- old wiring;
- hidden pipework;
- restoration;
- renovation work.
When the scope is uncertain, protect yourself through:
- contingency;
- clear exclusions;
- change orders.
Do not simply hope everything goes perfectly.
Use Change Orders
Suppose a contractor quotes:
£4,500
for a project.
During the work, the customer requests additional work worth:
£900.
Do not quietly absorb it.
Create a change order explaining:
- additional scope;
- added price;
- timeline change.
Get approval before continuing where practical.
Deposits for Larger Jobs
Deposits can protect cash flow.
They may help cover:
- materials;
- special-order products;
- equipment booking.
For example:
30% deposit
before ordering materials.
Then:
40% milestone payment
during work.
Then:
30% final payment
at completion.
The appropriate structure depends on:
- local law;
- contract terms;
- industry;
- project size.
Add Payment Processing Costs to Your Model
Online card payments are convenient.
But processing fees can reduce margin.
If a business processes:
£100,000
in card payments annually and pays around:
2–3%
in processing costs, that becomes a meaningful business expense.
Do not ignore it when building pricing.
Account for Callbacks and Warranty Work
No company completes every job perfectly forever.
You may occasionally need to:
- return;
- replace a part;
- correct work.
Those visits create cost.
A healthy pricing model should provide enough margin to absorb normal warranty and callback activity.
If one callback destroys all the profit from five jobs, pricing may be too tight.
Account for Bad Debt
Some customers will:
- pay late;
- dispute invoices;
- never pay.
Even with good payment systems, bad debt is part of business risk.
This does not mean adding a random “bad customer fee.”
It means setting margins that make the overall company resilient.
Know Your Break-Even Point
Your break-even point is where revenue covers all costs but produces no profit.
Suppose monthly fixed overhead is:
£20,000
and average gross margin is:
40%.
You need enough gross profit to cover that £20,000.
Required monthly revenue would be approximately:
£50,000
because:
40% of £50,000 = £20,000.
At that level:
Revenue: £50,000
Gross Profit: £20,000
Overhead: £20,000
Net Operating Profit: approximately £0 before other considerations.
Revenue above break-even begins creating operating profit.
Why Break-Even Matters
Without knowing break-even, an owner may celebrate:
£40,000 monthly revenue
even though the business needs:
£50,000
just to cover costs.
Revenue alone is not enough.
Calculate Revenue Per Technician
Another useful metric is:
Revenue per technician.
If four technicians generate:
£80,000/month
average revenue per technician is:
£20,000.
Track this alongside:
- billable hours;
- average ticket;
- gross profit.
It can help identify:
- underpricing;
- scheduling problems;
- low utilization.
Track Average Job Value
Formula:
Revenue ÷ Number of Jobs
Example:
Monthly revenue:
£60,000
Jobs completed:
150
Average job value:
£400
If you improve average ticket to:
£450
with the same 150 jobs:
Revenue becomes:
£67,500.
That is:
£7,500 more revenue
without adding another job.
Do Not Increase Prices Without Understanding Value
Higher pricing can improve profitability.
But customers also need to understand why your company is worth choosing.
Value can come from:
- faster response;
- qualified technicians;
- warranty;
- strong reviews;
- professional communication;
- better workmanship;
- cleaner service;
- easier booking.
Price and positioning should work together.
Offer Good, Better, Best Options
Some services work well with tiered choices.
For example:
Good
Basic replacement.
£650
Better
Higher-efficiency option.
£850
Best
Premium option with additional warranty.
£1,100
This helps customers choose based on:
- budget;
- preference;
- long-term value.
It also reduces the assumption that every sale depends on presenting the cheapest possible option.
Do Not Hide Necessary Costs
Avoid quoting a low price and then surprising the customer later with:
- travel;
- disposal;
- basic materials;
- admin charges.
If a charge is predictable, include it clearly in:
- quote;
- terms;
- pricing.
Transparency builds trust.
Review Prices Regularly
Costs change.
You may face increases in:
- wages;
- fuel;
- insurance;
- materials;
- software;
- rent.
A price book created three years ago may no longer be profitable.
Review pricing:
- quarterly;
- every six months;
- at least annually.
Also review after significant supplier or labor-cost changes.
Use Historical Job Data
The best pricing decisions come from your own jobs.
For each service, compare:
Estimated Labor
vs:
Actual Labor
Estimated Materials
vs:
Actual Materials
Quoted Price
vs:
Actual Gross Profit
Over time, this reveals where estimates are consistently wrong.
Example
You price drain clearing assuming:
1 hour.
But your last 50 jobs average:
1.8 hours.
That tells you your pricing model is outdated.
You can adjust the standard price using actual data.
Track Profit by Service Type
Some services may look attractive but produce weak margins.
Example:
Emergency Callouts
Revenue: £20,000
Gross Profit: £9,000
Bathroom Installation
Revenue: £30,000
Gross Profit: £6,000
Bathroom installations generate more revenue.
But emergency work creates more gross profit.
That insight can influence:
- marketing;
- pricing;
- staffing.
Track Profit by Customer Type
You may discover:
Residential
Average job:
£450
Gross margin:
40%
Commercial
Average job:
£2,500
Gross margin:
22%
Commercial brings larger invoices.
But residential may be more profitable percentage-wise.
Neither is automatically better.
Measure both.
What Happens When Your Price Is Too Low?
Symptoms include:
- always busy but no cash;
- owner works excessive hours;
- no money for new equipment;
- difficulty increasing wages;
- one callback wipes out job profit;
- constant pressure to book more work.
These can all be signs of underpricing.
What Happens When Your Price Is Too High?
Possible symptoms include:
- very low quote acceptance;
- customers repeatedly mention price;
- sales team struggles;
- competitor offers are consistently much lower.
But do not assume lower conversion automatically means pricing is wrong.
The issue may be:
- weak sales process;
- poor trust;
- unclear value;
- bad lead quality.
Measure Quote Acceptance Rate
Formula:
Accepted Quotes ÷ Quotes Sent × 100
Example:
100 quotes.
45 accepted.
Acceptance rate:
45%.
Track this over time.
If you raise prices and acceptance drops slightly but gross profit increases significantly, that may still be a positive outcome.
Price for Profit, Not Maximum Work
The goal is not necessarily:
win every quote.
If you win nearly every job, your price may be too low.
A healthy business needs enough margin to:
- pay its team;
- replace equipment;
- market itself;
- survive slow periods;
- grow.
Being busy is not the same as being profitable.
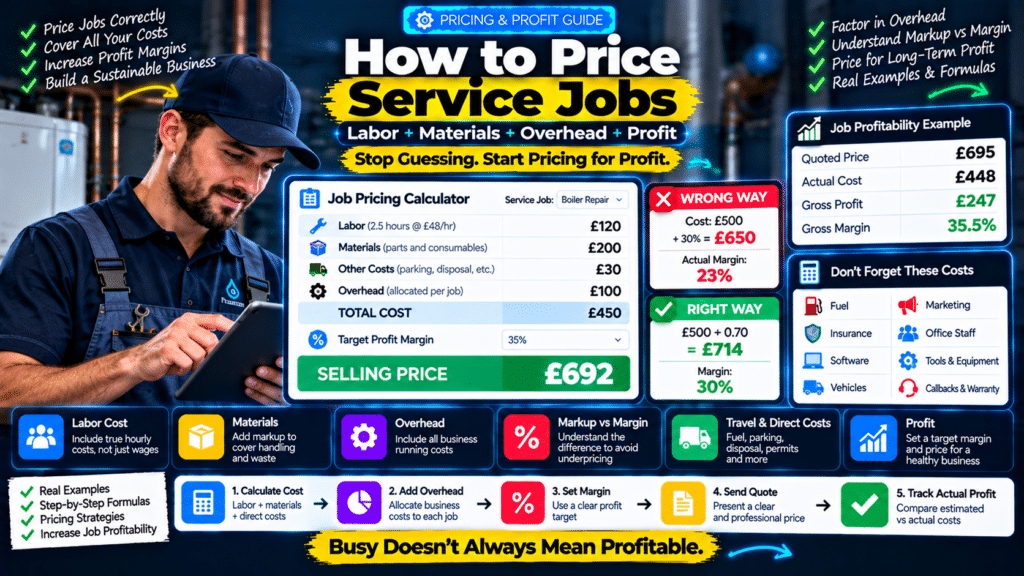
Simple Service Pricing Formula
A practical starting formula is:
Labor
Materials
Other Direct Costs
Overhead Allocation
=
Total Cost
Then:
Total Cost ÷ (1 − Desired Gross Margin)
=
Selling Price
Example
Labor:
£120
Materials:
£200
Direct costs:
£30
Overhead allocation:
£100
Total cost:
£450
Target gross margin:
35%
Selling price:
£450 ÷ 0.65
=
approximately:
£692
You could price the job at:
£695
depending on your standard price book.
Service Job Pricing Checklist
Before sending a quote, check:
- labor cost included;
- realistic labor time;
- materials included;
- waste considered;
- subcontractors included;
- equipment rental included;
- travel covered;
- overhead contribution included;
- payment fees considered;
- warranty risk considered;
- desired margin applied;
- tax handled correctly;
- customer scope clearly defined;
- exclusions clearly stated;
- change-order process defined.
Sources and Further Reading
These official resources back up the methods in this guide and are worth reading alongside it.
- Break-even point (U.S. Small Business Administration): the fixed costs ÷ contribution margin formula and a free break-even calculator.
- Write your business plan (U.S. Small Business Administration): building financial projections and pricing plans.
- What kind of records should I keep (IRS): the income and expense records your job costing should be built on.
Related guides
- How to Improve Gross Margin in a Service Business Without Just Raising Prices
- How to Calculate Gross Profit Per Job in a Service Business
- Revenue vs Profit vs Cash Flow: What Service Business Owners Need to Know
- Tools, Software and Automation for Trades: Start Here
Frequently Asked Questions
How do you price a service job?
Start by calculating:
- labor;
- materials;
- direct costs;
- overhead allocation.
Then add enough profit to reach your desired gross margin.
A useful formula is:
Selling Price = Total Cost ÷ (1 − Desired Margin)
What is the difference between markup and margin?
Markup compares profit with cost.
Margin compares profit with selling price.
For example, adding a 50% markup to a £100 cost produces a £150 selling price, which equals a 33.3% gross margin.
Should contractors charge hourly or fixed price?
Both can work.
Hourly pricing is useful when job duration is uncertain.
Fixed pricing works well for predictable, repeatable services and gives customers greater price certainty.
Should materials be marked up?
Many businesses mark up materials to recover:
- ordering;
- storage;
- handling;
- waste;
- inventory costs.
The appropriate markup varies by business.
What is overhead in a service business?
Overhead includes expenses required to operate the company that cannot easily be assigned to one specific job.
Examples include:
- insurance;
- software;
- office wages;
- marketing;
- vehicles;
- rent.
How do I calculate overhead per billable hour?
Divide total overhead for the period by the number of billable technician hours.
For example:
£10,000 monthly overhead ÷ 400 billable hours = £25 overhead per billable hour.
What gross margin should a service business target?
There is no universal number.
Your target depends on:
- industry;
- labor;
- materials;
- overhead;
- competition;
- business goals.
Calculate the margin your company actually needs rather than copying another business.
Should I include travel in my price?
Yes.
Travel consumes:
- technician time;
- fuel;
- vehicle capacity.
It may be recovered through:
- service charges;
- travel fees;
- fixed-price services.
How often should I update prices?
Review them regularly and whenever major costs change.
At minimum, an annual pricing review is sensible for many service businesses.
What is a minimum service charge?
A minimum service charge is the lowest amount you charge for sending a technician to a job.
It helps cover:
- travel;
- setup;
- technician time;
- overhead
even when the actual repair is very small.
Conclusion
Learning how to price service jobs properly is one of the most important financial skills a service-business owner can develop.
The biggest mistake is thinking:
Price = Labor + Materials
because the business also has to pay for:
- vehicles;
- insurance;
- marketing;
- office staff;
- tools;
- software;
- non-billable time.
A stronger formula is:
Labor
Materials
Direct Costs
Overhead
Profit
=
Selling Price
You also need to understand the difference between:
markup
and:
margin.
If a job costs:
£500
and you want a:
30% gross margin
the correct price is approximately:
£714
not:
£650.
As the business grows, build a price book so technicians are not inventing prices in the field.
Then compare:
estimated cost
with:
actual job cost.
Track:
- labor hours;
- materials;
- gross profit;
- quote acceptance;
- average job value.
The goal is not to be the cheapest company.
It is not even to win every quote.
The goal is to price work so the business can:
deliver good service
↓
pay the team properly
↓
cover overhead
↓
handle risk
↓
make a healthy profit
↓
keep growing
A fully booked calendar means very little if every job is underpriced.
Price with data instead of instinct, and the same amount of work can produce a much healthier business.



1 thought on “How to Price Service Jobs Without Guessing: Labor, Materials, Overhead & Profit”
Pingback: ChatGPT for Contractors: Prompts for Quotes & Emails