
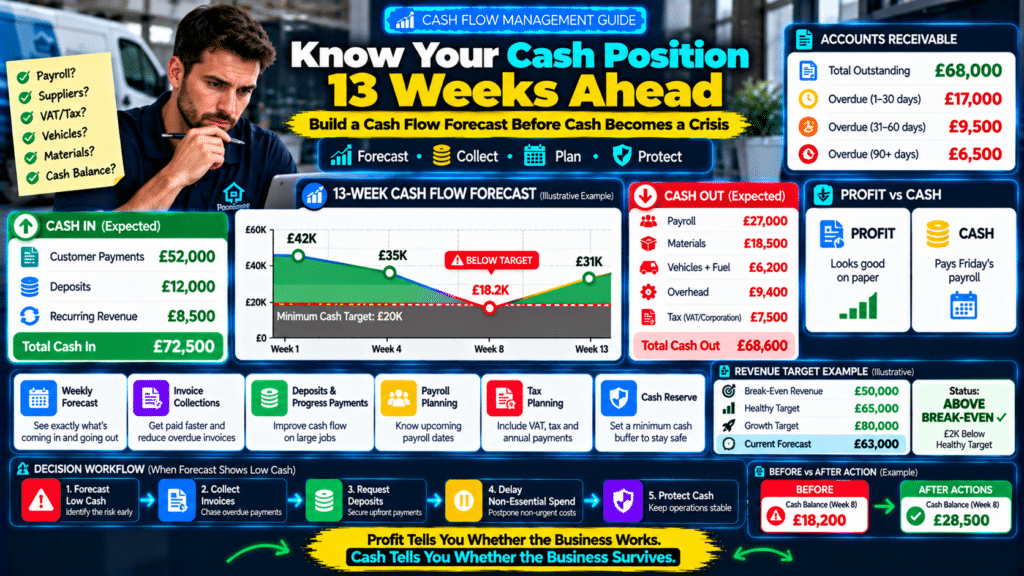
A service business can be profitable and still run out of cash.
That sounds contradictory.
It is not.
Imagine a contractor completes:
£30,000 of work this month.
But customers will not pay for another:
30–60 days.
Meanwhile, the business still has to pay:
- technicians;
- fuel;
- materials;
- insurance;
- vehicles;
- software;
- suppliers;
- tax obligations.
On paper, the business may have made money.
In the bank account, there may not be enough cash to cover Friday’s payroll.
That is why every growing service company should understand how to create a cash flow forecast for a service business.
A good forecast helps answer:
How much cash do we have now?
↓
What money should come in?
↓
What bills are going out?
↓
What will our bank balance look like next week?
↓
Will we have a shortage?
↓
What should we do before it happens?
One of the most practical forecasting methods for small and growing businesses is a:
13-week cash flow forecast.
It gives you roughly three months of visibility without requiring you to predict the entire year perfectly.
What Is Cash Flow?
Cash flow is the movement of money into and out of your business.
Cash Inflows
Money entering the business.
Examples:
- customer payments;
- deposits;
- recurring service payments;
- finance received;
- asset sales.
Cash Outflows
Money leaving the business.
Examples:
- payroll;
- materials;
- fuel;
- rent;
- insurance;
- software;
- tax payments;
- loan repayments.
The goal is not simply:
more money in than out eventually.
Timing matters.
Profit Is Not the Same as Cash
This is one of the most important financial concepts for a service-business owner.
Suppose you complete a:
£10,000 commercial electrical project.
Your accounting records may show:
£10,000 revenue.
But the customer has:
30-day payment terms.
You may need to pay:
- £3,000 materials;
- £2,500 wages;
- £500 vehicle and overhead costs
before receiving the £10,000.
That creates a cash-flow gap.
The job can be profitable while still putting pressure on the bank account.
Why a 13-Week Forecast Works Well
A 13-week forecast is useful because it is:
- short enough to estimate realistically;
- long enough to identify upcoming problems;
- easy to update weekly.
It covers roughly:
one quarter.
That gives you visibility into:
- payroll cycles;
- VAT or tax payments;
- supplier bills;
- vehicle payments;
- large jobs;
- seasonal changes.
What Should a Cash Flow Forecast Show?
At minimum:
Opening Cash
How much money is available at the beginning of the week?
Cash In
What payments are expected?
Cash Out
What expenses are expected?
Net Cash Flow
Cash In − Cash Out
Closing Cash
Opening Cash + Net Cash Flow
The closing balance becomes the next week’s opening balance.
Simple Example
Week 1
Opening cash:
£15,000
Customer payments:
£12,000
Cash available:
£27,000
Expenses:
£18,000
Closing cash:
£9,000
Week 2
Opening cash:
£9,000
Customer payments:
£8,000
Expenses:
£14,000
Closing cash:
£3,000
Now you can see a problem developing before the bank account becomes critical.
Step 1: Start With Your Real Bank Balance
Do not begin with:
I think we have around £20,000.
Use actual numbers.
Record:
- operating account;
- relevant business cash accounts.
Be careful not to count:
- unused credit limit;
- unpaid invoices
as cash already available.
If the money is not available to spend, it should not be included in opening cash.
Step 2: List Expected Customer Payments
This is where optimism can make forecasts useless.
Do not simply list:
all outstanding invoices
as cash coming in next week.
Ask:
When is the customer realistically expected to pay?
Example
Invoice #1048
Value:
£4,500
Due:
18 October
Customer normally pays:
10 days late.
Your forecast may be more realistic if payment is placed in:
late October
rather than exactly on the due date.
Forecast behavior.
Not hope.
Separate Confirmed and Expected Cash
Useful categories:
Confirmed
Examples:
- customer already paid;
- deposit scheduled;
- direct debit expected.
Highly Likely
Invoice due from reliable customer.
Uncertain
Quote not yet approved.
A quote should usually not be treated as cash until the business has enough confidence that:
- work will happen;
- payment timing is known.
Step 3: Include Deposits
Deposits can make a major difference to cash flow.
Imagine a project requires:
£8,000 materials.
If you collect:
40% deposit
before ordering materials, the customer helps fund the job.
Without a deposit:
the business funds the project itself.
That can become dangerous when several large jobs start together.
Example
Project value:
£20,000
Deposit:
£8,000
Materials:
£7,000
The deposit covers most of the initial material commitment.
That protects working capital.
Step 4: Include Recurring Revenue
Recurring service businesses have an advantage.
Examples:
- cleaning;
- landscaping;
- pest control;
- maintenance plans;
- pool service.
If you know:
£5,500
in recurring payments usually arrive each month, include them based on realistic timing.
Recurring revenue can make forecasting more predictable.
Step 5: List Payroll
For many service businesses, payroll is one of the largest cash outflows.
Add the actual dates.
For example:
Week 1
Payroll:
£9,500
Week 3
Payroll:
£9,500
The exact pattern depends on whether employees are paid:
- weekly;
- fortnightly;
- monthly.
Payroll should never be a surprise.
Step 6: Add Supplier Payments
Do not only record new material purchases.
Also include:
existing supplier invoices that will become due.
For example:
Supplier A
£3,200 due Week 2.
Supplier B
£1,450 due Week 3.
Equipment Supplier
£4,600 due Week 5.
Large material bills can create sudden cash pressure.
Step 7: Add Fixed Expenses
These are usually easier to forecast.
Examples:
- rent;
- vehicle payments;
- insurance;
- software;
- phone;
- internet;
- loan repayments.
Some happen monthly.
Others:
- quarterly;
- annually.
Annual payments are easy to forget.
Step 8: Add Variable Expenses
Variable costs change with workload.
Examples:
- fuel;
- materials;
- subcontractors;
- disposal;
- payment processing.
Estimate them using:
- scheduled jobs;
- historical averages.
If the next month is unusually busy, last month’s fuel number may not be realistic.
Step 9: Add Tax Obligations
Tax payments can cause serious cash-flow problems if they are ignored until the due date.
Depending on your location and company structure, this may include obligations such as:
- VAT or sales tax;
- payroll taxes;
- corporation/business taxes.
The specific rules depend on your jurisdiction, so forecasts should use figures provided or reviewed by your accountant or tax professional.
The key principle:
tax money is not necessarily available operating cash.
Step 10: Add Debt Payments
Include:
- vehicle finance;
- equipment loans;
- business loans;
- credit repayments.
Use actual payment dates.
Do not only track:
loan balance.
Cash forecasting is concerned with:
what leaves the account and when.
Step 11: Add Planned Purchases
If you expect to buy:
- new van;
- equipment;
- computers;
- tools;
include it.
For example:
Week 7
New equipment:
£6,000
Now you can see whether the purchase creates a cash shortage.
Perhaps you:
- delay purchase;
- finance it;
- build more cash first.
That is the value of forecasting.
Step 12: Calculate Weekly Net Cash Flow
Formula:
Cash In − Cash Out = Net Cash Flow
Example:
Cash in:
£15,000
Cash out:
£18,000
Net cash flow:
−£3,000
Negative cash flow for one week is not automatically a disaster.
The important question is:
What happens to the remaining cash balance?
Step 13: Calculate Closing Cash
Formula:
Opening Cash + Net Cash Flow = Closing Cash
Example:
Opening cash:
£10,000
Net cash flow:
−£3,000
Closing cash:
£7,000
Then:
Week 2 opening cash becomes:
£7,000.
Continue for 13 weeks.
Example 13-Week Forecast Structure
| Week | Opening Cash | Cash In | Cash Out | Net Flow | Closing Cash |
|---|---|---|---|---|---|
| 1 | £20,000 | £15,000 | £18,000 | -£3,000 | £17,000 |
| 2 | £17,000 | £12,000 | £14,000 | -£2,000 | £15,000 |
| 3 | £15,000 | £21,000 | £17,000 | +£4,000 | £19,000 |
| 4 | £19,000 | £9,000 | £22,000 | -£13,000 | £6,000 |
Week 4 clearly deserves attention.
Without forecasting, the owner may not notice until it arrives.
Build a Minimum Cash Threshold
Decide:
How low are we comfortable letting cash fall?
For example:
Minimum operating cash: £15,000
This is not necessarily your full emergency reserve.
It is a warning level.
If forecast cash falls below it:
management takes action.
Example
Forecast:
Week 6 closing cash:
£11,200
Minimum threshold:
£15,000
Gap:
£3,800
Now you have time to respond.
What Can You Do Before a Cash Shortage?
Possible actions include:
- collect overdue invoices;
- request deposits;
- delay non-essential purchases;
- negotiate supplier timing;
- reschedule capital spending;
- reduce unnecessary expenses;
- use an appropriate pre-arranged credit facility.
The important difference is:
you act before the crisis.
Chase Receivables Earlier
Do not wait until cash is low to discover:
£40,000 of invoices are overdue.
Track accounts receivable.
Useful buckets:
- current;
- 1–30 days overdue;
- 31–60;
- 61–90;
- 90+.
Older debt generally deserves more attention.
Example
Outstanding invoices:
£60,000
But:
£20,000 is current.
£15,000 is 1–30 days overdue.
£10,000 is 31–60.
£15,000 is over 90 days.
Your:
£60,000 receivables
are not equal to:
£60,000 reliable cash next week.
Forecast accordingly.
Invoice Quickly
If a job is completed Friday but the invoice is not sent until:
next Wednesday
you have added five days to the payment cycle before the customer even sees the bill.
A better workflow:
Job Completed
↓
Invoice Generated
↓
Invoice Sent Same Day
↓
Payment Clock Starts
Faster invoicing improves cash timing.
Ask for Progress Payments
Large projects can create cash problems if payment only occurs at the end.
Example:
£30,000 project
Instead of:
£0 upfront
↓
Business funds entire project.
Use a payment schedule where appropriate:
30% Deposit
↓
40% Milestone
↓
30% Completion
The structure should match:
- project;
- contract;
- applicable law.
Avoid Funding Customer Projects Yourself
If the business pays:
- materials;
- wages;
- subcontractors
months before receiving payment, it is effectively financing customers.
Some credit terms are normal.
But understand the cost.
This matters especially with:
- commercial contracts;
- construction projects;
- property management clients.
Cash Flow Problems Can Grow With Revenue
This surprises many owners.
A business grows from:
£50,000/month
to:
£100,000/month.
Sounds excellent.
But now it needs:
- twice the materials;
- more payroll;
- more vehicles;
- more fuel.
If customers pay slowly, growth can consume cash faster than profit replenishes it.
This is known as working-capital pressure.
Growth needs financing.
Profitable Growth Still Needs Cash
Imagine:
Each job generates:
20% net profit eventually.
But the company must pay:
80% of costs
before customer payment.
The faster the company grows:
the more money it needs upfront.
That is why:
growth planning
and:
cash planning
must work together.
Scenario Planning
Do not create only one forecast.
Create:
Base Case
What you realistically expect.
Conservative Case
What if customers pay slower?
Growth Case
What if bookings increase?
This helps you understand risk.
Example Conservative Scenario
Base forecast assumes:
£50,000 receipts
next month.
Conservative scenario:
£38,000.
What happens?
If cash goes negative:
you know the business has little room for error.
Stress-Test Large Customers
Imagine one customer owes:
£25,000.
Ask:
What happens if they pay 30 days late?
If that one delay prevents payroll:
the company is financially dependent on that customer.
That is valuable information.
Forecast by Week, Not Only Month
Monthly forecasting can hide timing problems.
Imagine October shows:
Cash In: £80,000
Cash Out: £70,000
Looks fine.
But:
£50,000 of receipts arrive on:
October 28.
Payroll of:
£20,000
is due:
October 10.
Monthly totals hide the shortage.
Weekly forecasts reveal it.
Update the Forecast Every Week
A 13-week forecast should roll forward.
Every week:
- record actual results;
- remove completed week;
- add a new Week 13;
- update expected payments;
- update expenses.
It should stay current.
Compare Forecast vs Actual
Example:
Forecast customer receipts:
£20,000
Actual:
£14,000
Difference:
−£6,000
Why?
Maybe:
- customer paid late;
- job delayed;
- quote lost.
Forecast accuracy improves when you investigate differences.
Build Better Payment Assumptions
Over time you may learn:
Residential Customers
Average payment:
same day.
Commercial Customers
Average payment:
38 days.
Then your forecasts become more realistic.
Use historical behavior.
Track Days to Payment
Useful metric:
Average Days to Payment
If this rises from:
12 days
to:
22 days
cash flow may deteriorate even if sales stay constant.
Monitor it.
Track Accounts Receivable
Useful metrics include:
- total unpaid invoices;
- overdue invoices;
- average payment time;
- receivables over 30/60/90 days.
These directly influence the forecast.
Cash Flow Forecast vs Budget
These are different.
Budget
Plans:
- revenue;
- expenses;
- profit
over a longer period.
Cash Flow Forecast
Tracks:
when cash actually enters and leaves the bank.
A business should ideally use both.
Cash Flow Forecast vs Profit & Loss
A profit-and-loss statement tells you whether the company generated accounting profit.
The cash flow forecast tells you whether you can:
pay next week’s bills.
Both matter.
Build a Cash Reserve
A forecast is even more useful when combined with a cash reserve.
A reserve gives the business protection against:
- slow months;
- large repairs;
- unexpected tax bills;
- customer payment delays.
The right reserve depends on:
- overhead;
- revenue stability;
- industry;
- debt;
- risk.
There is no single universal amount.
Calculate Monthly Operating Costs
Suppose core monthly expenses are:
£35,000.
A reserve target might be discussed in terms of:
months of operating expenses.
For example:
£35,000 × 2 months = £70,000
Whether two months is appropriate depends on the business.
The forecast helps show how much risk exists.
Separate Tax Money Where Practical
Some owners use a separate account for funds expected to cover tax obligations.
This can reduce the temptation to treat all bank cash as:
available profit.
Discuss the appropriate setup with your accountant.
Do Not Use Revenue as Your Cash Metric
The company may announce:
We did £100,000 this month.
But ask:
How much cash did we actually collect?
Revenue matters.
Collections matter too.
Track Cash Conversion
Useful operational sequence:
Lead
↓
Quote
↓
Job
↓
Invoice
↓
Payment
Every delay adds time before cash arrives.
Improve each step.
Example
Old Process
Quote approval: 4 days.
Job completion: 7 days.
Invoice delay: 3 days.
Customer payment: 21 days.
Total:
35 days
Improved Process
Quote approval: 2 days.
Job completion: 5 days.
Invoice same day.
Payment: 14 days.
Total:
21 days
Cash arrives two weeks sooner.
That can materially improve the business.
Cash Flow and Pricing
Poor cash flow is not always a collection problem.
Sometimes prices are simply too low.
If each job produces insufficient margin:
more jobs may still fail to generate enough cash.
Review:
- pricing;
- gross margin;
- overhead.
Cash flow forecasting helps expose the symptom.
Job costing may identify the cause.
Cash Flow and Inventory
Too much inventory traps cash.
Example:
Van and warehouse stock:
£80,000
but:
£25,000
has not moved in 12 months.
That money could otherwise support:
- payroll;
- marketing;
- investment.
Stock is an asset.
But it is not as liquid as cash.
Cash Flow and Vehicles
Vehicles can consume substantial cash through:
- deposits;
- monthly payments;
- repairs;
- insurance.
Before adding a van, place the cost into your 13-week forecast.
Ask:
Can the business comfortably support this?
Not simply:
Can we get finance approval?
Cash Flow and Hiring
Hiring creates additional outflows before the technician becomes fully productive.
New technician may require:
- wage;
- training;
- van;
- tools;
- software;
- uniform.
Put those costs into the forecast before hiring.
This connects directly with Blog #79.
Create a Weekly Cash Meeting
A 20-minute weekly financial meeting can review:
Current Cash
Expected Receipts
Overdue Invoices
Upcoming Payroll
Major Bills
13-Week Low Point
Then decide actions.
Keep it practical.
Cash Flow Dashboard
A useful dashboard might show:
Current Cash: £42,000
Receivables: £68,000
Overdue Receivables: £17,000
Next Payroll: £13,500
Lowest Forecast Balance: £18,200
Minimum Cash Target: £20,000
Status:
ACTION REQUIRED
Now the owner can make decisions earlier.
Watch the Lowest Point, Not Just Today
Today’s bank balance may look healthy.
Example:
Current:
£50,000
But forecast:
Week 8: £4,000
because:
- payroll;
- tax;
- vehicle purchase
all happen close together.
The forecast is designed to reveal that future low point.
Create Cash Alerts
Set simple triggers.
Green
Forecast remains above:
£30,000.
Yellow
Below:
£20,000.
Red
Below:
£10,000.
Your actual thresholds depend on the business.
The purpose is to make action systematic.
Avoid Overly Complicated Forecasts
You do not need 200 categories.
Start with major items.
Cash In
- residential customers;
- commercial customers;
- deposits;
- recurring revenue.
Cash Out
- payroll;
- materials;
- subcontractors;
- vehicles;
- fuel;
- overhead;
- tax;
- debt;
- equipment.
You can add detail later.
Spreadsheet Structure
A practical spreadsheet can have:
Rows: cash categories.
Columns: Week 1 through Week 13.
For example:
| Category | W1 | W2 | W3 | W4 |
|---|---|---|---|---|
| Opening Cash | ||||
| Customer Receipts | ||||
| Deposits | ||||
| Total Cash In | ||||
| Payroll | ||||
| Materials | ||||
| Vehicles | ||||
| Overhead | ||||
| Tax | ||||
| Total Cash Out | ||||
| Closing Cash |
Simple is enough to begin.
Common Cash Flow Forecast Mistakes
Counting Quotes as Cash
A quote is not money.
Assuming Every Invoice Pays on Time
Use actual customer behavior.
Forgetting Tax
A classic cash-flow surprise.
Ignoring Annual Bills
Insurance and subscriptions can create spikes.
Forecasting Only Monthly
Weekly timing matters.
Never Updating the Forecast
An old forecast quickly becomes useless.
Being Too Optimistic
Forecast realistically.
Ignoring Overdue Invoices
Collections should be actively managed.
Focusing Only on Sales
Revenue and cash are not identical.
No Minimum Cash Target
You need a warning level.
13-Week Cash Flow Checklist
Each week confirm:
- Opening bank balance updated
- Expected customer payments reviewed
- Overdue invoices reviewed
- Deposits included
- Payroll entered
- Supplier payments entered
- Fixed costs entered
- Variable costs updated
- Tax dates included
- Loan payments included
- Planned equipment purchases included
- Lowest cash point reviewed
- Minimum cash threshold checked
- Actions assigned where needed
Sources and Further Reading
These official resources back up the methods in this guide and are worth reading alongside it.
- Manage your finances (U.S. Small Business Administration): bookkeeping, financial statements and cash flow basics.
- Write your business plan (U.S. Small Business Administration): building financial projections.
Related guides
- How to Calculate Gross Profit Per Job in a Service Business
- How to Calculate Break-Even Revenue for a Service Business
- Tools, Software and Automation for Trades: Start Here
Frequently Asked Questions
What is a cash flow forecast?
A cash flow forecast estimates when money will:
- enter;
- leave
your business over a future period.
It helps predict future bank balances.
What is a 13-week cash flow forecast?
It is a weekly forecast covering approximately three months.
It is commonly useful because it provides near-term visibility without requiring highly uncertain long-range predictions.
Why can a profitable service business have cash flow problems?
Because revenue and cash collection happen at different times.
The business may pay:
- wages;
- materials;
- suppliers
before customers pay their invoices.
How often should I update my cash flow forecast?
A 13-week forecast is typically most useful when updated weekly.
Should unpaid invoices be included?
Yes, but place them in the week you realistically expect payment rather than assuming every invoice will be paid immediately.
Should quotes be included?
Usually not as confirmed cash.
Unapproved quotes are uncertain.
What is negative cash flow?
Negative cash flow means more money leaves the business during the period than comes in.
It is not automatically bad if the company has enough cash and the outflow was planned.
How can I improve service-business cash flow?
Common strategies include:
- invoice faster;
- collect deposits;
- improve overdue invoice follow-up;
- use progress billing;
- manage expenses;
- price jobs properly.
Should I forecast weekly or monthly?
Weekly forecasting is often better for near-term cash management because it reveals timing problems that monthly totals can hide.
Do I still need an accountant?
A cash-flow forecast is a management tool and does not replace professional accounting, bookkeeping, tax, or financial advice.
Conclusion
A cash flow forecast for a service business helps answer one of the most important questions an owner can ask:
Will we have enough cash when we need it?
Do not rely only on:
sales
or:
profit.
Track:
Cash Today
↓
Customer Payments
↓
Payroll
↓
Supplier Bills
↓
Tax
↓
Equipment
↓
Closing Cash
A simple 13-week forecast can reveal problems weeks before they become emergencies.
That gives you time to:
- collect overdue invoices;
- request deposits;
- delay non-essential purchases;
- adjust spending;
- plan financing properly.
The strongest process is:
Forecast
↓
Compare to Actual
↓
Update Every Week
↓
Identify the Lowest Point
↓
Take Action Early
A healthy bank balance today does not guarantee a healthy balance eight weeks from now.
And a profitable business can still fail if it cannot meet its obligations when they become due.
The goal of cash-flow forecasting is not to predict every pound perfectly.
It is to give the owner enough visibility to make better decisions before:
cash becomes a crisis.



1 thought on “How to Create a Cash Flow Forecast for a Service Business: 13-Week Guide”
Pingback: Slow Season Service Business Plan: Prepare for Winter